Case study: managing fluctuating cognitive capacity during a pension review
How a boutique Surrey IFA paused an uncharacteristic drawdown request, verified an existing LPA, and supported a client to decide safely.
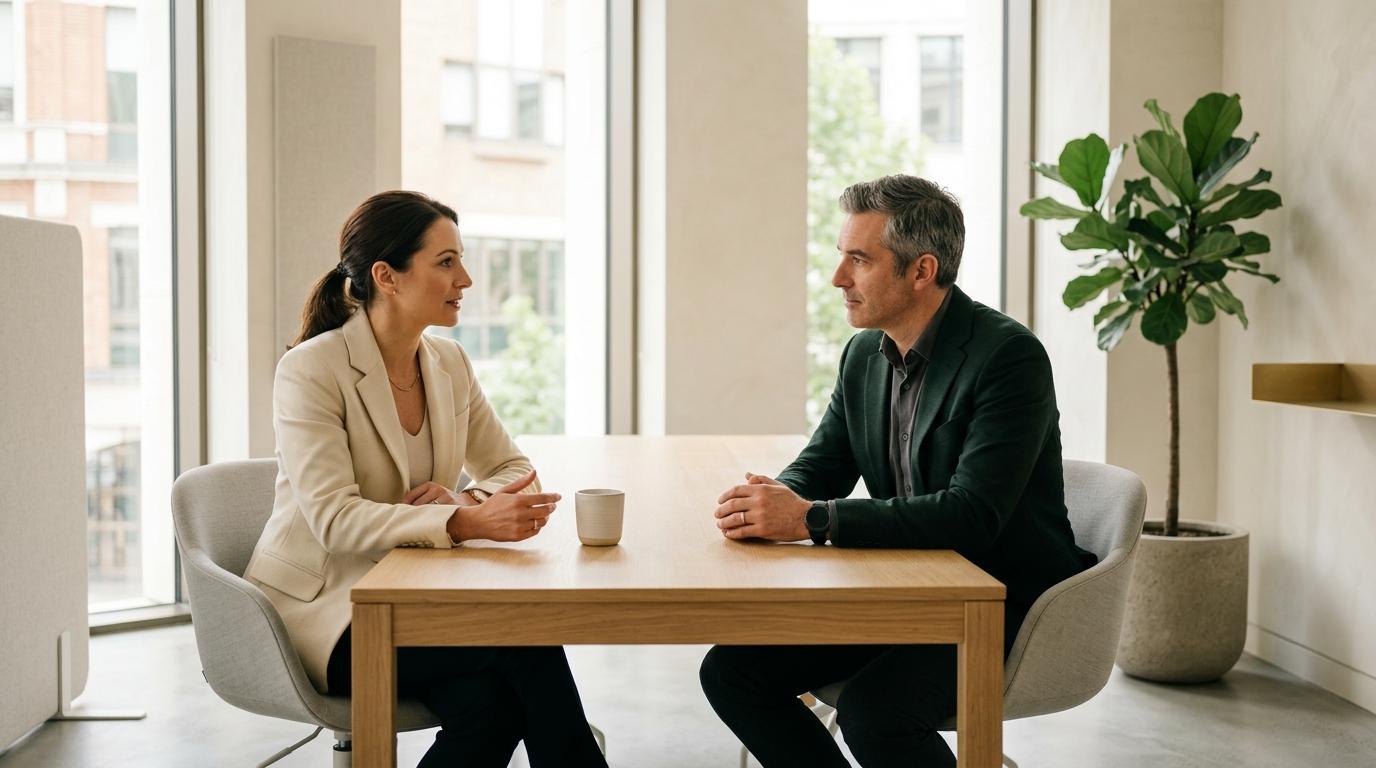
Eight years of annual reviews give an independent financial adviser a dependable baseline for how a client thinks, questions figures, and weighs tax trade-offs. When a 79-year-old pension drawdown client arrived at a six-person Surrey IFA practice for a 3:30pm review, the contrast was immediate. Usually meticulous about his personal allowance and portfolio charges, he forgot two £8,000 ad hoc withdrawals taken earlier in the tax year, repeated the exact same question about basic-rate income tax three times within twenty minutes, and abruptly asked to encash £45,000 and move his entire portfolio into cash.
Those observations pointed beyond everyday vulnerability into a decision-specific mental capacity question under the Mental Capacity Act 2005. Health drivers such as cognitive decline, infection, or medication side effects frequently overlap with fluctuating capacity. Without playing doctor, the adviser recognised clear functional red flags: the client could not retain core tax and withdrawal facts long enough within the conversation to weigh up the irreversible tax charge and long-term income shortfall that a £45,000 withdrawal would cause.
Handling the pause with warmth preserved trust and dignity. Rather than confronting the client or suggesting he was confused, the adviser explained calmly that a withdrawal of that size and a full asset reallocation merited fresh tax projections before signing anything. He wrapped up the afternoon session gently, walked the client out, and immediately wrote dated, strictly factual notes avoiding all medical speculation before escalating the file to the compliance director (SMF16) the same afternoon.
Internal review anchored every next step in the statutory principles of the Mental Capacity Act 2005: presume capacity unless established otherwise, and take all practicable steps to help the person make their own decision before restricting access. Checking previous review notes revealed two vital details: the client had mentioned earlier in the year that afternoon blood-pressure medication left him tired, and he had already registered a Property and Financial Affairs Lasting Power of Attorney naming his daughter three years earlier.
At 9:45am the following morning, the adviser telephoned the client when he felt rested and alert. Speaking gently without alarm, the adviser noted that yesterday's late afternoon slot had felt long and asked whether a shorter 10am meeting with large-print summary notes sent ahead would feel easier. With the client's clear verbal explicit consent under UK GDPR Article 9, the firm recorded his morning appointment preference and fatigue disclosure, and gained his explicit agreement to invite his daughter along to the follow-up review. Three working days ahead of the meeting, the paraplanner posted a crisp two-page summary in 18-point sans-serif type.
Ahead of the rescheduled session, the firm verified the daughter's Property and Financial Affairs LPA cleanly using the 13-character GOV.UK online access code rather than asking her to post certified copies. The compliance director checked that the daughter was appointed sole attorney, confirmed no restrictions barred pension discussions, and verified that the LPA included explicit wording permitting discretionary investment management should formal attorney authority ever be required in future.
During the calmer 10am session, the difference in comprehension was unmistakable. Referring comfortably to his large-print summary, the client recalled both earlier £8,000 withdrawals accurately, explained clearly that he only needed £15,000 to cover roof repairs rather than £45,000, and confirmed he wished to retain his existing balanced investment mandate once the adviser showed the higher-rate tax impact of taking more. To guard quietly against undue influence or third-party pressure, the adviser addressed every key question directly to the client, checked that his daughter let him answer in his own words without steering, and confirmed the withdrawal bank account remained in his sole name with no unusual recent payee changes.
Following the meeting, the firm processed the proportionate £15,000 withdrawal safely in line with COBS suitability rules, sent a concise large-print suitability letter to the client, and posted a copy to his daughter in line with his recorded permission. Because capacity can change over time, the adviser agreed with the client to switch from annual reviews to shorter six-monthly morning check-ins rather than waiting a full twelve months to re-verify comprehension. The completed file contained dated objective observations from both meetings, the UK GDPR consent audit trail, the OPG verification code confirmation, the practicable timing and format adjustments delivered, and clear evidence of how the client understood and articulated his final decision.
Presenting the anonymised file at its half-year governance committee prompted two lasting upgrades across the practice. The firm added an optional "preferred time of day and trusted contact" check to every annual review pre-meeting pack and tightened its internal fluctuating-capacity escalation guide so paraplanners and advisers follow the exact same calm pause protocol whenever unexpected confusion surfaces.
Practical answers for UK regulated firms
1Should the IFA have blocked the client from speaking about his pension once memory lapses appeared?
No. Under the Mental Capacity Act 2005, firms must presume capacity and take practicable steps such as better timing and large-print summaries before concluding a client cannot make a specific decision.
2Why did the firm check for a discretionary management clause inside the LPA?
In wealth management, standard Property and Financial Affairs LPAs do not automatically authorise an attorney to delegate investment decisions to a discretionary fund manager unless explicit permission is written into the instructions section.
3What details belong on the client file in a fluctuating mental capacity case?
Log dated, objective observations without medical diagnoses, the practicable adjustments offered, explicit UK GDPR consent, LPA verification details, and clear evidence of how the client understood and weighed the final instruction.
4How does an adviser check for undue influence when an attorney or family member attends?
Address questions directly to the client, observe whether the companion repeatedly interrupts or insists on large withdrawals benefiting themselves, and spend a brief moment speaking with the client alone where any concern arises.
5What would the firm have done had the client remained unable to understand the withdrawal at 10am?
The adviser would have paused the non-urgent instruction again, escalated to the compliance director, and considered whether formal invocation of the registered Property and Financial Affairs LPA or an independent clinical capacity assessment was needed.